By George Mayo, co-founder of Swiped. Published October 26, 2026.
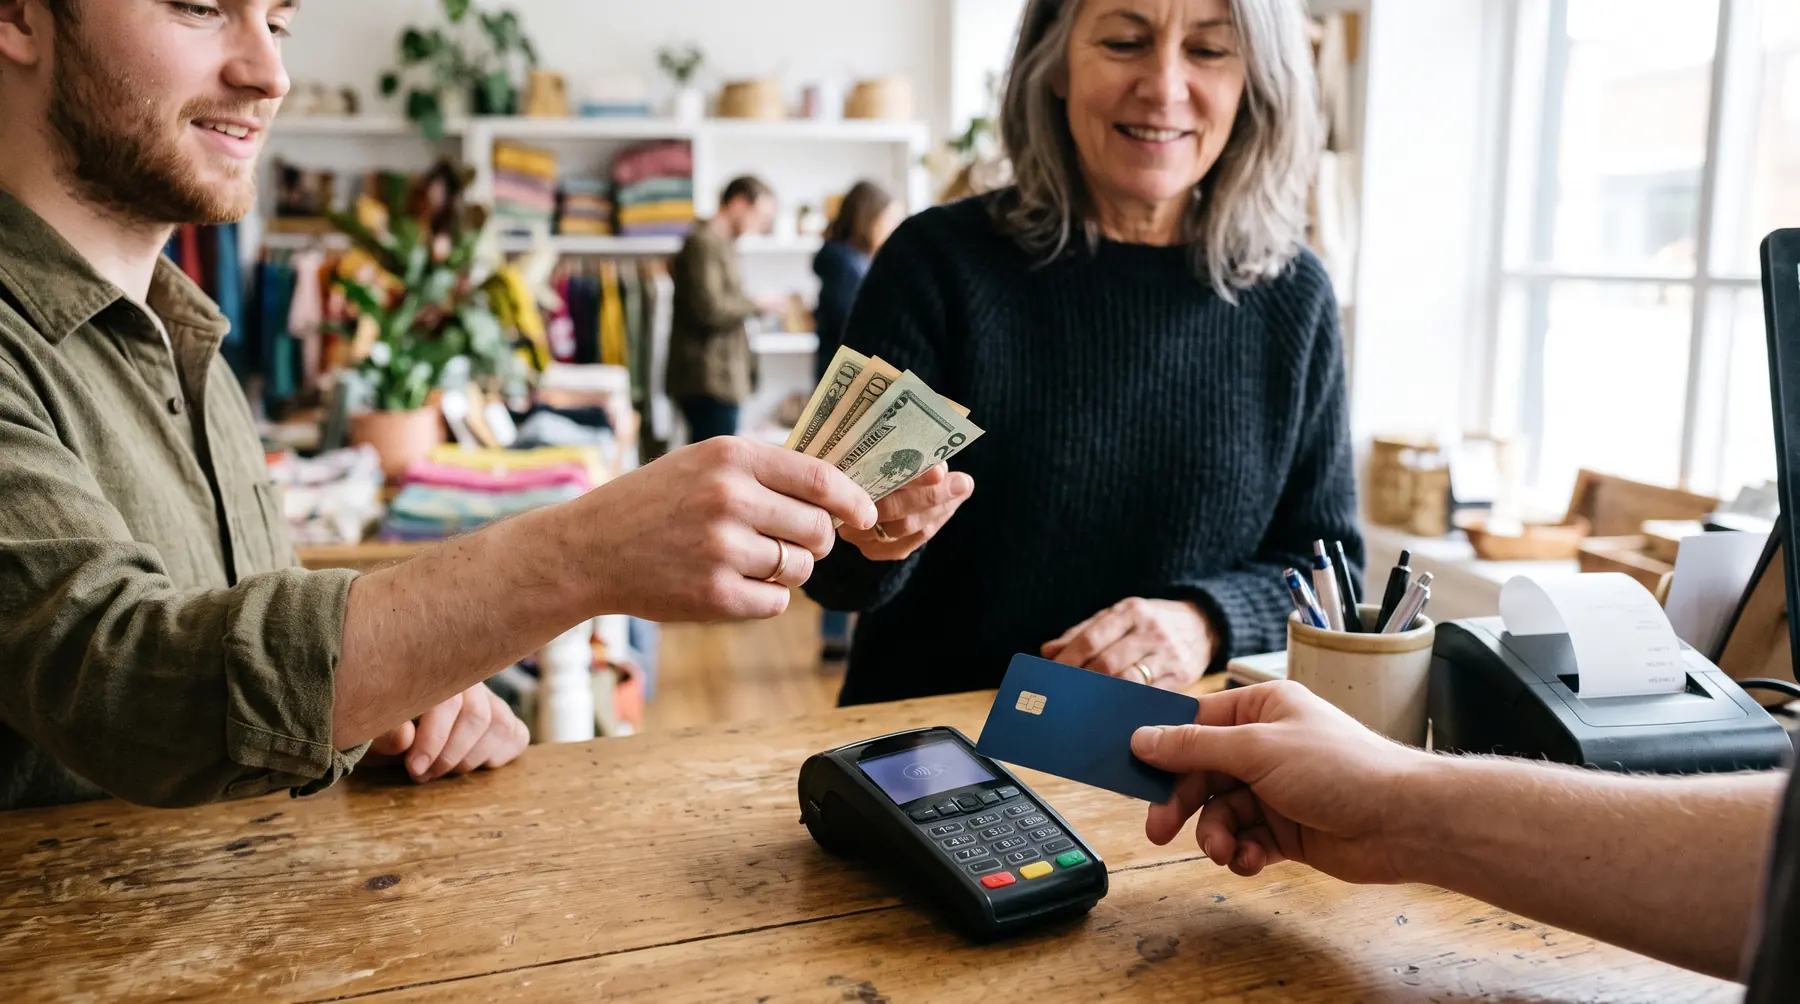
A cash discount program posts one price that includes the cost of accepting cards and gives customers who pay cash a small discount at the register. In New Jersey it is governed by card brand rules, not by the 2023 surcharge statute, which regulates fees added on top of a price.
Owners ask us two questions before anything else: is this legal, and what do I have to put on the wall. Here is the answer to both, with the sources, and the checklist we run before any program goes live.
Is a cash discount legal in New Jersey?
Yes. New Jersey's 2023 law, P.L.2023, c.146, regulates credit card surcharges: fees added to the price for card payers. A cash discount takes an amount off the posted price for cash and is not a surcharge under that law. Card brand rules allow it when the posted price is the card price and the discount is disclosed.
The Division of Consumer Affairs FAQ on the surcharge law is the clearest public statement of where the line sits. A bill introduced in the 2026 session, S595, would add notice requirements for cash discounts and card minimums. It has not been enacted as of this writing, and we track it.
How is it different from a surcharge?
A surcharge starts from a cash price and adds a fee for credit cards. It cannot exceed your actual processing cost in New Jersey, must be disclosed before the sale, and cannot be applied to debit or prepaid cards under card brand rules. A cash discount starts from the card price and subtracts for cash, so there is no fee to add and no debit split to manage.
That difference is why we set up the cash discount way. The register has less to decide, the receipt is simpler, and the customer who pays with a card sees exactly the price on the shelf or the menu.
What has to be on the wall and the receipt?
Clear signage that the posted price is the card price and that cash receives a discount, placed where the customer sees it before paying, and a receipt that shows the discount as its own line. We supply the signage and the receipt template with every install.
- Signage at the counter or host stand, visible before payment
- Menus and price tags show the posted (card) price
- Receipt prints the cash discount as a separate line
- Staff script: the price is the price; cash gets a small discount
What about debit cards?
How debit is treated is decided on your account before go-live and printed on your quote. The register applies the rule automatically by reading the card, so nobody at the counter has to ask what kind of card it is.
Getting this wrong is the most common mistake in do-it-yourself programs. It is a configuration setting, and we check it on the first statement.
What is the setup checklist?
Rate review, program sizing to your card mix, merchant account configuration, terminal or POS programming, signage, receipt template, staff walkthrough, and a first-statement review. Processor paperwork is filed before the program is switched on.
- Rate review on one recent statement
- Program configured on the merchant account, not improvised at the register
- Terminal or POS programmed and tested with a card and with cash
- Signage installed, receipt line verified
- First statement reviewed with you and adjusted to the quote
Will customers push back?
Most do not notice. The price is the price, and the discount reads as a bonus for cash. Owners tell us questions stop within the first week. We go live on a slow day and stay reachable through the first weekend.
Sources
About The Author
George Mayo co-founded Swiped and owns NJ POS Systems. He has worked in merchant services since 1994, when he and Mario Parisi founded Merchant Services Inc, which they built for twenty years and sold in 2014. He still reviews statements and quotes himself. More about the founders.
Related